
The holiday season is coming, and Boot Barn (BOOT) is getting ready for the shopping that comes with it.
Boot Barn operates more than 580 stores across 49 U.S. states, selling cowboy boots, denim, work boots, and ranch apparel. Although the stock has had a tough 2026, Wall Street wants to see whether the company can pull off a strong holiday quarter.
BOOT shares are down about 28% this year, but the stock has increased by roughly 20% over the past five trading days. That recent bounce followed the company’s second-quarter results. Bank of America then added another round of support.
In early November, BofA analyst Chris Nardone, who covers softlines and consumer retail for the bank, met with Boot Barn’s management and was impressed by their plans.
Because of that and the company’s recent results, he kept his Buy rating and $166 price target on BOOT. That price target implies about a 24% increase from the stock’s recent $133 share price.
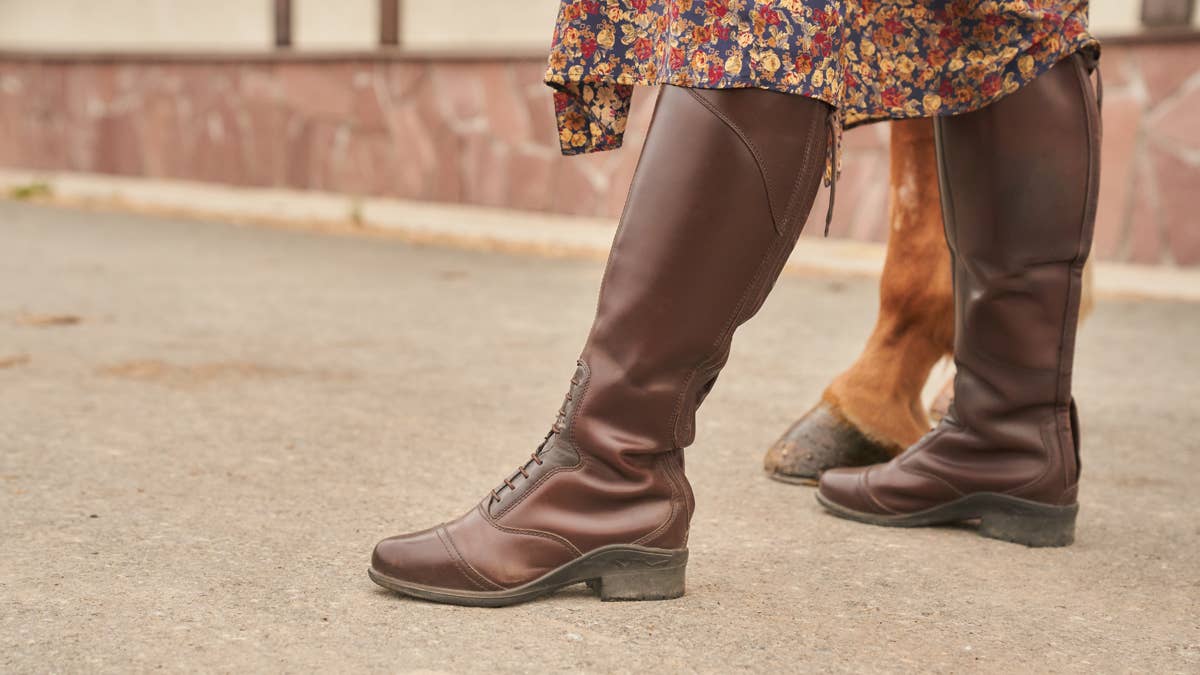
A women’s boot refresh aimed squarely at Black Friday
Boot Barn’s leadership has been clear that their women’s fashion boots are a weak spot for the company. However, CEO John Hazen told BofA that the company is moving fast to fix that.
Boot Barn is bringing in more color options and higher-priced fashion styles in time for Black Friday. The company has also featured the new boots in Boot Barn’s holiday gift guide and national TV ads so they can bring more shoppers into stores.
Also read: Kroger cuts discounts, promises pricing changes
Men’s boots are also showing a few signs of weakness. In Boot Barn’s fiscal second quarter of 2027, sales of men’s rubber-soled Western boots slowed. The company’s management isn’t sure yet whether the reason was the warm weather or customers being more careful with their spending because of the economic situation.
Even so, the company’s management remains hopeful about the holiday season. In the company’s October earnings release filed with the SEC, Hazen said Boot Barn is “excited about the holiday season,” pointing to refreshed products, improved stores, and a bigger national marketing push.
Why BofA still sees Boot Barn stock as a bargain
BofA still sees BOOT as a bargain because of its valuation. Boot Barn trades at about 14 times its expected earnings over the next two years.
Nardone thinks that’s low for Boot Barn, especially since he expects the company to grow its earnings by 15% next year, once tariff refunds are stripped out. In the BofA note shared with me, Nardone described the stock as “cheap relative to its growth profile.”
Related: Walmart gets aggressive when it comes to holiday sales
That growth, especially, has been a worry for investors. The company’s share price fell in 2026 because investors were worried about tariffs, softer fashion sales, and whether the company’s growth could keep up with new store openings.
However, Boot Barn is easing some of those worries, and the company is still expanding.
On the second-quarter earnings call, Hazen said that “given the strength of our real estate pipeline, we are increasing our fiscal 27 new store opening plans from 70 stores to a range of 75 to 80 stores.”
That’s a sign that the company’s growth plan remains intact, even if the stock does not reflect it.
The quiet growth engine most investors aren’t talking about
One part of Boot Barn’s business that I think gets overlooked is Boot Barn Workforce, the company’s B2B division that sells safety-toe boots, high-visibility clothing, and flame-resistant gear to other businesses rather than individual shoppers.
Today, that part of the business brings in about $100 million a year. Hazen also said it could grow 40% to 50% in the coming years, The Motley Fool reported.
More Retail Stocks:
- CVS split leaves shareholders with two stocks and three big questions
- Nike CEO admits blind spot as Jordan and Dunk sales shrink
- Nike’s Jordan sneaker pullback could have a surprising winner
A major reason Boot Barn Workforce is expected to grow so much is the artificial intelligence boom.
Companies building data centers are hiring thousands of electricians and other experts to set up the facilities needed to train AI models. Those workers need tough boots and work clothes every day, creating an opportunity for Boot Barn Workforce to become their main supplier.
What investors should consider before buying BOOT now
Some risks could still affect BOOT shares. Freight and shipping costs could rise next year, which could reduce the company’s margins. The reason for the slowdown in men’s boots is also still not fully explained.
After a 20% rally in just five days, some of the good news is probably already priced in. In addition, if the company’s Black Friday numbers disappoint, a pullback would not be a surprise.
The company’s outlook seems more encouraging for patient investors. Boot Barn keeps adding stores, and it’s improving margins on its own brands such as Cody James. Boot Barn is also quietly building a B2B business that is linked to the AI buildout.
That kind of growth mix usually rewards investors who can wait out a few rough quarters.
More Stocks News