
October Odds Moved With the Clock
The range matters more than a single headline probability. At 9:21 a.m. Eastern on 14 October, FXStreet reported that CME FedWatch put the chance of an October increase at about 50%, up from 22% before the CPI release. Later that day, at 7:23 p.m. Eastern, FXStreet put the October probability at 31.6% and the December probability at 89.7% in a separate market update. These are snapshots of futures pricing, not a poll of Fed officials or a promise about the decision.
Other outlets captured 49% after the release and 33.8% later that day, also citing CME. CME calculates probabilities from 30-day federal funds futures, so prices and implied odds can change as fresh data or Fed comments alter rate expectations.
Polymarket is a separate market with different participants and contract mechanics. Its October decision market briefly moved close to 50% after the inflation release, according to contemporaneous coverage, before retreating. An early 15 October snapshot from a Polymarket market-data tracker showed a 21.5% probability for a 25-basis-point increase. That lower reading should be read with its timestamp and venue attached, not averaged mechanically with CME’s futures-based numbers.
The Headline Was Energy-Heavy, but Core Was Firm
Consumer prices increased 0.6% in September and 3.7% over 12 months, up from 3.4% in August. Gasoline rose 9.1% and accounted for more than half of the monthly increase, according to the BLS. Core CPI, which excludes food and energy, advanced 0.3% month over month and 2.6% year over year. Both figures were above economists’ expectations of 0.2% and 2.5%, respectively, according to CNN’s report on the release.
The core monthly pace did not accelerate from August, when it also rose 0.3%. That gives policymakers two readings to weigh: a large energy shock lifted the headline, while underlying inflation remained stronger than forecast but did not quicken from the previous month. FinanceFeeds’ CPI analysis examined the gasoline surge and the core miss. A separate market report tracked Bitcoin’s response as rate expectations changed.
Williams Said There Was No Need to Rush
New York Fed President John Williams said after September’s move that “there is no need for urgency” and that policymakers had time to gather more information. In his 29 September speech, he also said that, if the economy followed his forecast, “one further upward adjustment” might be appropriate “late this year.” Williams’ remarks support the case for another increase in 2026, but they do not specify October.
The distinction is important because the September meeting minutes already showed broad support for keeping another increase under consideration. As FinanceFeeds reported on the minutes, officials’ year-end projections did not amount to a commitment to act at the next meeting. Williams’ speech likewise describes a conditional outlook based on incoming data.
December Is More Firmly Priced
At 7:23 p.m. Eastern on 14 October, CME FedWatch put the chance of a December increase at 89.7%, according to FXStreet. The probability reflects the futures market’s implied distribution, and it can change as new information arrives. A higher December reading alongside a lower October probability suggests traders were shifting the expected timing of a move, not abandoning the possibility of further tightening.
That timing distinction matters across the curve: a hold in October can leave December live, while an October hike brings tightening forward. FinanceFeeds’ earlier analysis showed how futures and prediction markets can disagree.
Gold illustrates how the timing question can influence assets beyond rates. The metal does not pay interest, so a higher expected policy path can raise the opportunity cost of holding it, although safe-haven demand can pull in the other direction. FinanceFeeds tracked gold ahead of the release in its September CPI market analysis.
Retail Sales and PPI Arrive Before the Decision
The September retail sales report and producer price index are scheduled for 15 October, giving markets fresh evidence on household demand and business costs. The Census Bureau release calendar lists retail sales for that day. Retail sales are nominal and do not adjust for inflation, so a stronger result would not by itself show that real consumer spending accelerated. The Fed will also consider employment, financial conditions and the inflation data already available.
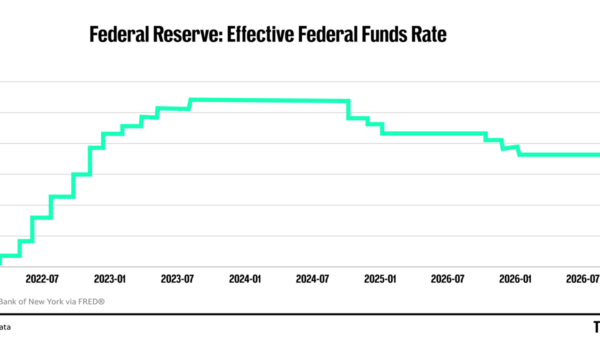
The next CPI report is scheduled for 10 November, after the October meeting. The Committee therefore must decide without another monthly CPI reading, although the October 27–28 meeting calendar and the September policy statement are available from the Federal Reserve. The September increase lifted the target range to 3.75%-4.00%, its first hike since 2023.
The evidence leaves a timing question, not a settled October call. The 3.7% headline and above-forecast core reading revived hike bets, but the energy contribution, Williams’ remarks and the pullback in pricing argue against treating any one snapshot as the Fed’s decision.