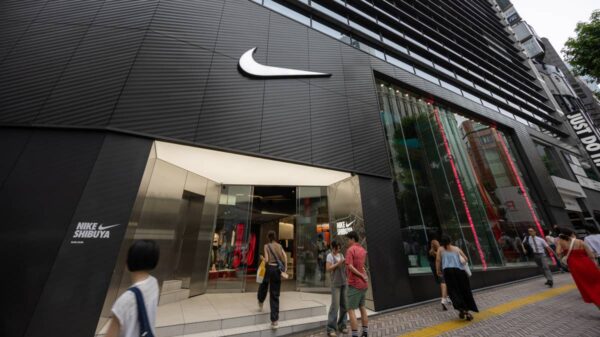



S&P Dow Jones Indices said on 4 September that Nike will be removed from the S&P 100 as part of its quarterly rebalance. The index provider gave the timing as “effective prior to the open of trading on Monday, September 21, 2026.”
Funds that replicate the S&P 100 will therefore need to sell Nike by the time the new composition takes effect. Nike is staying in the S&P 500, which means funds tracking the broader benchmark are not required to change their holdings.
What Changes on 21 September
Nike is one of four companies leaving the S&P 100. Honeywell Aerospace, Simon Property Group and Colgate-Palmolive are also being removed, while Dell Technologies, Palo Alto Networks, Arista Networks and Sandisk are entering. All four additions are classified as information-technology companies.
S&P said the changes make each index more representative of its market-capitalization range. It did not publish a company-specific judgment about Nike’s management, products or future earnings, so the removal should be read as an index-composition decision rather than an analyst downgrade.
The change follows earlier FinanceFeeds coverage of what Nike’s S&P 100 exit changes. That analysis also explains why Nike’s continued membership in the S&P 500 limits the scale of mandatory selling.
Only S&P 100 Trackers Have to Sell
The largest dedicated tracker, the iShares S&P 100 exchange-traded fund, held $20.08 billion in net assets on 15 September. Nike recently represented about 0.1% to 0.2% of that fund, implying mechanical selling measured in tens of millions of dollars from that product rather than billions.
Other funds and institutional mandates tracking the same index will also rebalance. Managers usually execute much of that activity near the closing auction before the effective date, when liquidity is concentrated and they can reduce tracking error against the revised benchmark.
The flow is therefore known, but its price effect is not. Arbitrage desks can buy or sell in advance, discretionary investors may take the other side and the closing auction can absorb a large part of the order. A previous MSCI proposal involving crypto-linked companies showed why the amount of benchmarked capital matters more than the fact of an index change alone.
The Exit Follows Two Difficult Business Years
Nike’s removal arrives during a turnaround under Chief Executive Elliott Hill. Nike’s latest annual results showed fiscal 2026 revenue of $46.4 billion, flat as reported and down 2% on a currency-neutral basis.
Fourth-quarter revenue fell 1% to $11.0 billion and declined 4% in currency-neutral terms. Direct revenue dropped 7% as reported, including a 12% fall in digital sales, while wholesale revenue increased 4%. The split shows Nike rebuilding retail partnerships after its earlier emphasis on direct distribution.
Quarterly gross margin rose to 49.2%, but Nike said an expected $986 million tariff recovery provided about 900 basis points of benefit. The reported margin therefore cannot be treated as an entirely operating-led improvement. Greater China and Europe, the Middle East and Africa remained sources of revenue pressure.
Those figures provide business context for the reduction in market value discussed in FinanceFeeds’ analysis of Nike’s replacement by technology companies. They do not establish that the index deletion itself changes Nike’s revenue, cash flow or turnaround prospects.
Europe Gets a Parallel Rebalance the Same Day
The US change coincides with a European index review. Among the changes, Nokia and Engie enter the EURO STOXX 50 before the open on 21 September, while Volkswagen and Wolters Kluwer leave, creating mandatory buying and selling for funds that track that benchmark.
FinanceFeeds has examined both the assets tied to the Nokia rebalance and the mechanical flow affecting Nokia and Volkswagen. The comparison shows why investors must distinguish between a widely tracked index and a narrower benchmark before estimating the likely trading impact.
What Nike Holders Should Read Into the Removal
The deletion creates a dated sell order for passive S&P 100 funds, but it does not remove Nike from the broader large-cap market. Most investors holding Nike through an S&P 500 fund will see no portfolio change on 21 September.
For direct shareholders, the rebalance may increase volume and short-term price noise around the preceding close. The longer-term case still depends on product demand, wholesale recovery, direct sales, China and underlying margins. Index membership summarizes Nike’s reduced relative size; it does not decide whether the turnaround succeeds.