
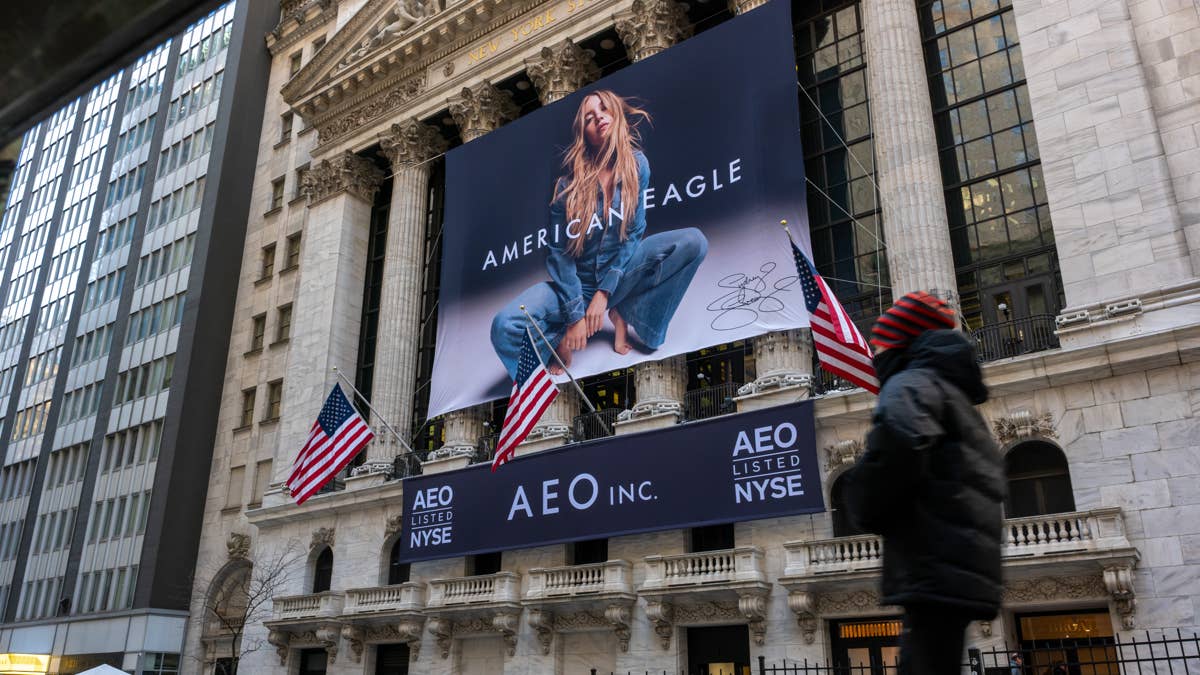
American Eagle Outfitters has been leaning on surging growth at Aerie recently, but Bank of America warns that the momentum may not be enough to overcome problems at its namesake brand.
BofA reinstated coverage of American Eagle Outfitters (AEO), but with an Underperform rating and a $16 price objective.
The firm argued that a turnaround at the American Eagle brand will take longer than expected.
The bank expects American Eagle comparable sales to remain negative in the second quarter, then improve to roughly flat in the second half of fiscal 2026.
It does not expect the brand’s sales to turn positive until fiscal 2027.
“We think uncertainty on AE’s comp trajectory and pressure from investments will likely temper upside,” BofA analyst Mary Sport wrote in a note shared with TheStreet.
The call comes even as American Eagle Outfitters as a whole entered the year with strong sales growth.
American Eagle struggles while Aerie surges
American Eagle Outfitters reported record first-quarter revenue of $1.2 billion, up 10% year over year, while comparable sales increased 8%.
Operating profit reached $28 million, ahead of the company’s guidance.
But the performance of its two largest brands looked different.
More Retail:
- Dollar General copies Costco’s playbook with a discount twist
- Pepsi and Coca-Cola bet big on soda Americans say they want
- Iconic supermarket chain closes more stores and facilities
Aerie’s comparable sales jumped 25%, helping the brand surpass $2 billion in trailing 12-month revenue.
Meanwhile, comparable sales at American Eagle declined 2%.
CEO Jay Schottenstein acknowledged the divide in May, saying American Eagle’s results were “mixed” and that the retailer was working to improve its women’s business, product execution, and brand positioning.
BofA isn’t convinced the changes will produce a quick turnaround.
The bank models American Eagle comps to decline another 2% in the second quarter, then be roughly flat in the back half.
It expects fiscal 2026 comps for the brand to decline about 1%.
More concerning, BofA’s data suggests American Eagle’s difficulties may not simply reflect weaker spending among younger consumers.
The bank said its aggregated credit and debit card data showed teen clothing spending accelerated in July, while third-party data tracking American Eagle indicated deteriorating sales.
Observed American Eagle sales were down 15% year over year in the week ending August 2, according to Bloomberg Second Measure data cited by BofA.
Aerie sales were up 12%, and OFFLINE sales jumped 29% during the same week.
That divergence supports BofA’s view that American Eagle still has an assortment problem, rather than its weakness being driven entirely by a soft apparel market.
Aerie may not be able to carry American Eagle forever
So far, Aerie has provided a major cushion for the retailer, but BofA expects its extraordinary growth rate to cool.
The bank estimates Aerie comps will rise 18% in the second quarter, then slow to 8% in the third quarter and 4% in the fourth quarter as the brand begins comparing against exceptionally strong prior-year results.
Aerie accounts for roughly 35% of AEO’s business, according to BofA.
Which means that even Aerie’s double-digit growth has not been enough to fully offset declines at the larger American Eagle brand.
The bank models Aerie’s comp growth settling at about 4% in fiscal 2027.
Profitability presents another challenge.
American Eagle raised its full-year SG&A growth forecast to the high-single-digit range following its first-quarter results, reflecting increased spending, including advertising investments.
The company nevertheless maintained its fiscal 2026 operating income outlook of $390 million to $410 million.
BofA expects those expenses to continue growing faster than sales, limiting earnings improvement.
It forecasts adjusted second-quarter EPS of 20 cents, below Visible Alpha consensus of 22 cents, while estimating that operating income will fall nearly 57% from a year earlier to about $45 million.
“The impressive growth at Aerie has not been enough to offset declines at AE,” BofA said.
And if Aerie’s growth begins to normalize before American Eagle fixes its assortment, the retailer could lose its strongest offset.
Shoppers are still buying, but selectively
American Eagle’s struggles are occurring as consumers grow more selective about where and when they spend on apparel, rather than abandoning the category altogether.
Bank of America data showed U.S. clothing spending increased 3.5% year over year in July, down from 6.9% in June as demand from the World Cup and Prime Day faded.
The bank said consumers are increasingly concentrating purchases around major promotional periods.
That behavior is also showing up at value-focused retailers.
BofA said discount-apparel spending increased 4% in the second quarter, while the number of transactions contributed to growth for a sixth consecutive month in July.
A McKinsey research also found that consumers are becoming more price-conscious.
More than 80% of consumers across price segments said good value for money is a top purchasing factor.
And they exhibited value-seeking behavior, such as waiting for sales or shopping across retailers before making a purchase.
But value does not necessarily mean buying the cheapest product.
Strategy&, PwC’s strategy consulting business, identified “smart value” as a major theme in fashion retail for 2026.
It argues retailers increasingly need the right combination of price, quality, and trend relevance to win purchases.
That distinction is relevant for American Eagle.
BofA’s own card data showed teen clothing spending accelerated in July, even as third-party data cited by the bank showed worsening sales trends at American Eagle.
The divergence has led BofA to conclude that the brand’s weakness is tied partly to its assortment rather than a broader collapse in demand for teen apparel.
It suggests today’s apparel shopper may still be willing to spend, but retailers have to give them a stronger reason to do it.
Related: Chicken dining chain franchisee files Chapter 11 bankruptcy