
The retail sector has had a tough year. Many shoppers have cut back on spending, and rising shipping costs are squeezing company profits.
Ocean freight rates are currently up about 8%, and the spike is expected to hit retailer margins almost immediately through domestic fuel surcharges, according to a Bank of America industry note.
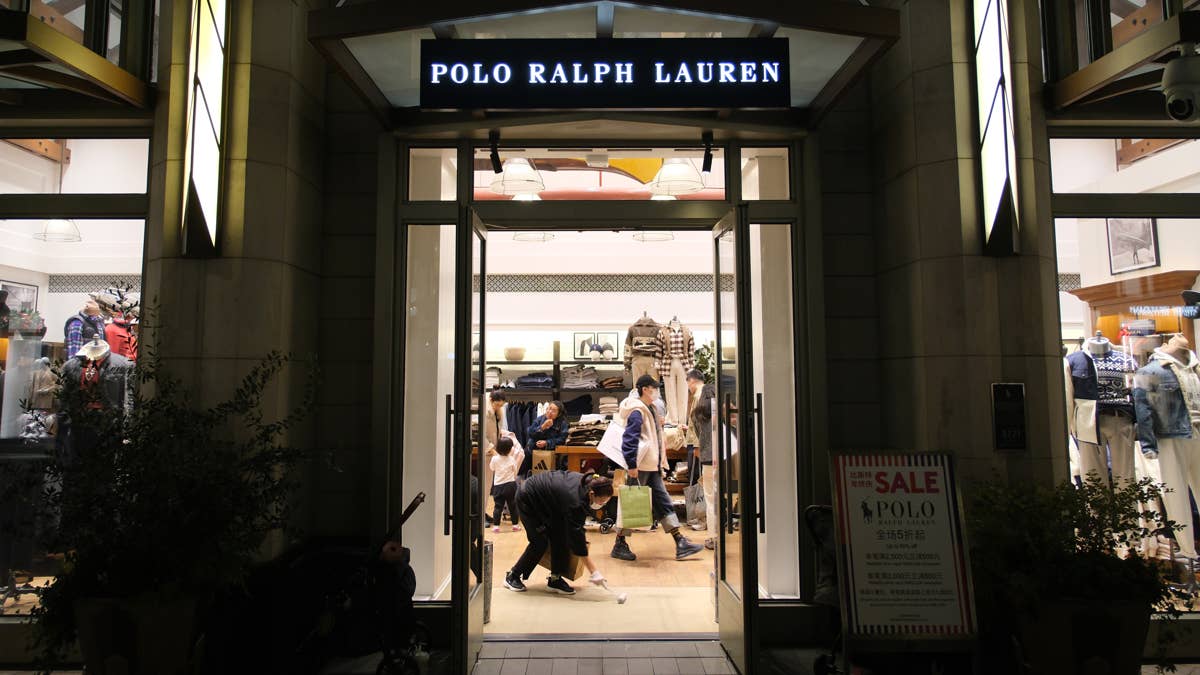
Recent Citi data reported by Reuters showed that in September, luxury credit card spending dropped by 6% from the previous year. However, Ralph Lauren (RL) is not feeling the effects as much as other companies.
Some Wall Street analysts have stayed positive on Ralph Lauren through most of 2026. On Oct. 12, 2026, Bank of America analyst Kendall Toscano reaffirmed her Buy rating and kept her $450 price target on RL.
Her reason for believing in the stock even though the whole retail sector is slowing down is simple. Ralph Lauren skews to a higher-income customer base that has remained resilient and is still spending, despite tougher economic conditions.
Why Ralph Lauren’s shoppers are still buying
Lower- and middle-income households continue to be strained, according to a recent KPMG note.
Toscano wrote that the “RL core customer is doing just fine.” She pointed out that the business still has steady demand across its stores, with North America showing a solid increase in the first quarter.
Europe growth was more modest, with BofA expecting continued share gains despite macro pressure, and Asia, led by strong demand in China, is driving most of the company’s growth, as Ralph Lauren reported.
Also read: BofA gives Starbucks investors key customer insight before earnings
She also noted that “impressive global brand momentum remains intact,” and that the company beat earnings expectations by about 7% in its fiscal 2027 first quarter.
BofA believes the company will beat expectations again when it reports second-quarter results in early November.
What’s behind BofA’s $450 price target
Toscano thinks the worries about shipping costs that have pushed the stock lower are unnecessary.
Shipping makes up only about 5% of what it costs Ralph Lauren to make its goods, Benzinga reported. And the company already agreed on fixed prices for its ocean shipping earlier in the year, so sudden fuel spikes won’t hit it as hard.
Related: Starbucks CEO reveals what he thinks will keep customers coming back
She also expects Ralph Lauren to gain more profit from every sale next quarter. Toscano forecasts roughly a 90-basis-point expansion in operating margin and a 60-basis-point gain in gross margin year-over-year, driven by higher average unit retail prices and a favorable product mix.
“RL has a track record of expanding margins through significantly greater headwinds like tariffs,” Toscano wrote.
How Ralph Lauren actually makes its money
Some of you might already be familiar with Ralph Lauren. The company designs and sells premium clothing, accessories, home goods, and fragrances under brands like Polo Ralph Lauren and Lauren Ralph Lauren.
More Retail Stocks:
- Ross Stores enters a new market as customers hunt for low prices
- Levi’s CEO admits the company missed the biggest jeans trend of the year
- Procter & Gamble could face new cost problem
In the first quarter of fiscal 2027, the company brought in about $1.96 billion in revenue, a roughly 14% increase from a year earlier. That shows its sales are still up.
Ralph Lauren also charges more without losing customers by improving its product quality. The company’s average selling prices have roughly doubled over the last eight years, but only about 25% of that came from charging more for the same items.
What everyday RL investors should watch
Ralph Lauren is a good reminder that some retail businesses are still up. If you’re interested in the stock, watch for its operating profit margin when it reports second-quarter results. Beating expectations there again would back up BofA’s call.
There’s always a risk involved, though. Ralph Lauren’s European sales could weaken further, slowing its overall sales. That’s why I often advise investors to sit tight until the earnings report, when you can confirm the trend.
More Stocks News