
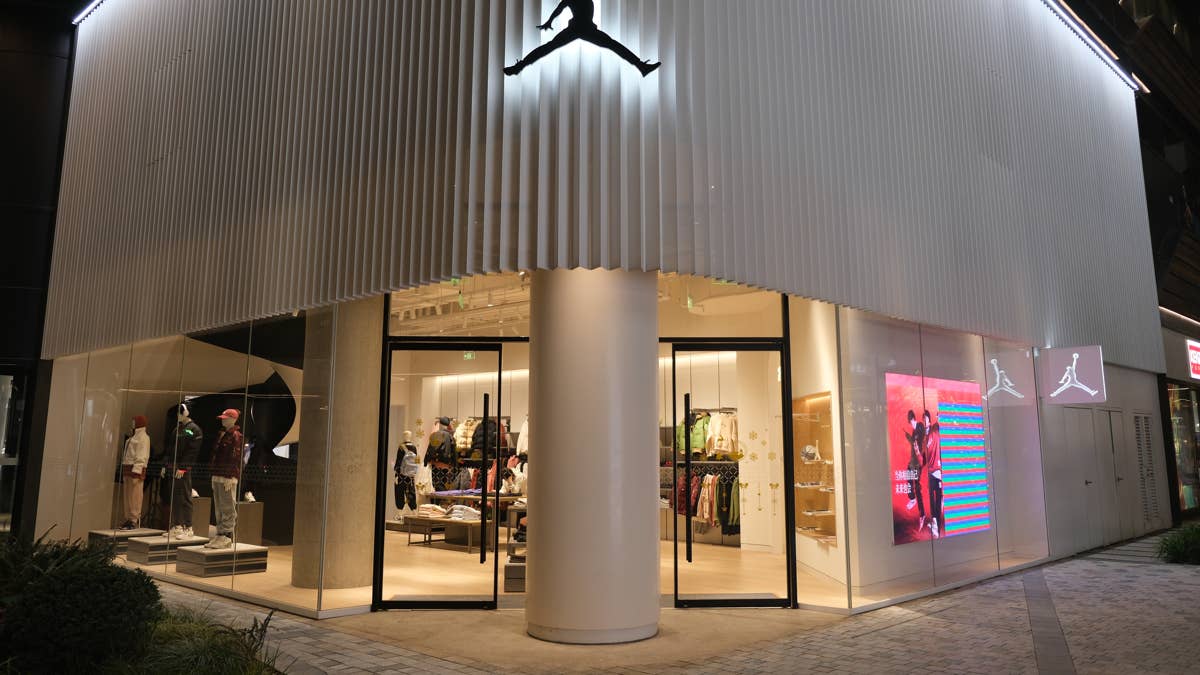
For years, a new Air Jordan release worked like a holiday. Sneaker fans set alarms, refreshed the app, and paid resale prices when they missed out.
That scarcity was the product. Lately, Nike has been rolling out so many retro pairs that the magic has worn off — and the company now admits it.
Nike (NKE) is still the biggest name in athletic footwear, with roughly 40% of the global market, according to Bank of America. It brought in about $46.4 billion in revenue in fiscal 2026, which ended in May.
Management insists the core of the business is healthy. “The Sport Offense is driving measurable progress across our performance business,” CEO Elliott Hill said in Nike’s fiscal first-quarter earnings release.
The rest of the house is another story. “Simply put we’ve been oversupplying our iconic retro product,” Hill said on the company’s earnings call.
“When consumers see the Jumpman, it should feel special. It should feel earned,” he added.
According to a Bank of America research report shared with me, the damage from that oversupply, and from China, will last longer than the bank expected just a week ago.
Nike guidance falls far short of Wall Street’s bar
Nike’s revenue fell 4% to $11.2 billion in the quarter ended Aug. 31, or 5% on a currency-neutral basis, the company reported Oct. 1. Nike Direct sales dropped 8%, and Converse sank 28%.
The outlook was worse.
“We currently expect revenues to decline in the high single digits range,” CFO Dave Denton said on the call, guiding to adjusted earnings of $1.15 to $1.35 a share for fiscal 2027.
That range sits well below the $1.67 consensus Bank of America cited from Visible Alpha. Shares fell about 9% in premarket trading Oct. 2 to roughly $32, the lowest since September 2013, Roic.ai reported, leaving the stock down about 45% this year.
Read more: Nike making its most famous sneakers harder to buy
Bank of America analyst Lorraine Hutchinson cut her price target to $24 from $30 and reiterated an Underperform rating in her report, titled “Another reset.” It was her second cut in about a week, after she downgraded Nike from Neutral with a $30 target on Sept. 25, 24/7 Wall St. reported.
“Despite another significant reduction to our estimates, we continue to see downside risk to the premium multiple until the timing of a revenue inflection becomes clearer,” wrote Hutchinson.
The new target sits about 32% below the stock’s $35.15 close before the report and values Nike at 16 times the bank’s fiscal 2028 earnings estimate. Hutchinson also cut her fiscal 2027 and 2028 earnings forecasts by 21% and 22%.
Jordan retros and China drag on sales
Sportswear made up about half of Nike’s first-quarter sales and declined at a low double-digit rate, while Jordan Brand, 13% of sales, fell in the mid-teens, Hutchinson wrote.
The bigger worry is what happens next with retailers. “Several higher-volume footwear styles sold through below expectations, leaving excess inventory and resulting in lower wholesale order books for the coming seasons,” wrote Hutchinson.
Hill acknowledged the same problem. “Looking ahead, that has impacted our future order books as we proactively work with our wholesale partners,” he said on the call.
More Retail:
- Major shareholder could force Barbie maker to consider a sale
- Department store chain bets on a new shopping experience
- British fashion brand that went bankrupt reopens its first store
China is a tougher fix. Retail sales of consumer goods there rose just 0.4% in August from a year earlier, according to official data reported by the Qatar News Agency.
Local rivals Anta Sports and Li Ning have also been winning over Chinese shoppers, XTB analysts noted after Nike’s previous quarter.
Nike’s own trend is getting worse. Greater China sales fell 9% in the year-ago quarter, Benzinga reported, compared with a 26% constant-currency drop this time, according to Bank of America.
“In the near-term, revenues and profitability in China will be impacted,” Hill said.
Given that backdrop, it’s easy to see why Hutchinson expects no quick rebound. “We expect the reset to take multiple seasons and weigh on both sales and profitability,” wrote Hutchinson.
She isn’t the only skeptic. Goldman Sachs trimmed its target to $30 from $38 with a Neutral rating, as we reported at TheStreet, and Morgan Stanley rates the stock Underweight with a $27 target, according to Roic.ai.
Bank of America pins the recovery on running shoes
There is a bright spot.
“If we were to exclude the reset in Greater China, Nike Performance would have been up low double digits in Q1,” Denton said.
“Running is up double digits again with consistent share gains,” Hill added.
Hutchinson agrees running is working, but she sees it as only a down payment.
“The eventual sales turn will depend on growing levels of newness to drive stronger customer interest,” wrote Hutchinson, who expects innovation to take center stage at Nike’s November investor day.
Much will likely depend, however, on whether Nike can fund that comeback without straining its payout. Bank of America projects $1.64 a share in dividends for fiscal 2027 against just $1.13 in earnings, which means Nike would pay out more than it earns.
The bank does model $2.8 billion in free cash flow that year, enough to cover roughly $2.4 billion in dividends. “The dividend remains a significant priority in our capital allocation strategy,” Denton said.
Nike is also leaning on a new cost program called Pace, which Bank of America said targets $2.5 billion in gross savings by fiscal 2031.
In my view, that’s the real test for income investors. A dividend yield near 5% looks generous, but it now rests on cost cuts that haven’t been delivered yet.
Hutchinson laid out the risk plainly for anyone tempted by the beaten-down stock.
“Earnings increasingly depend on gross margin expansion and cost control, leaving downside risk to estimates and the multiple if execution falls short,” wrote Hutchinson.