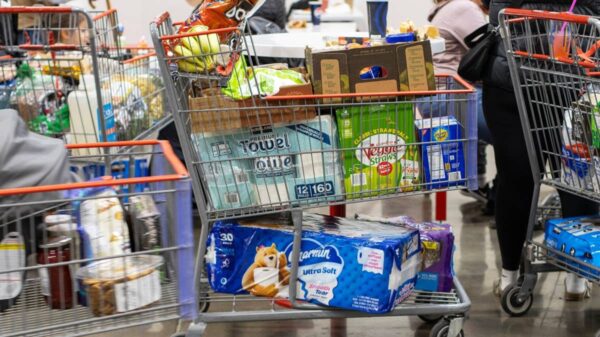

Costco built the business by convincing shoppers that its annual membership fee pays for itself through lower prices, bulk savings, and access to products they may not find elsewhere.
More than 145.2 million people have Costco cards, me among them.
People with large families are more likely to take out memberships for redeemable points, cash back, and wholesale prices.
Costco saw a 39.4% increase in memberships between 2020 and 2025, according to data from Capital One Shopping.
This formula has held up as consumers have become more selective about spending, helping Costco continue to post strong sales and traffic growth.
But the challenge now is protecting this value proposition as transportation, merchandise, and other supply-chain costs put pressure on margins.
This tension is at the center of Bank of America’s latest report on Costco Wholesale (COST), shared with TheStreet ahead of its fiscal fourth-quarter earnings.
Costco will report its Q4 earnings on Sept. 24.
Bank of America lowers Costco price target
BofA analyst Christopher Nardone lowered the firm’s price objective on Costco to $1,095 from $1,200 while maintaining a Buy rating.
The lower target reflects a more cautious view of Costco’s margins, even as the firm remains bullish on the company’s sales growth, membership model, and ability to keep taking market share.
More Costco:
- Costco keeps discontinuing popular products
- Discontinued Costco member favorite returns to shelves
- Costco’s new service beats Amazon at its own game
The firm also trimmed its fiscal 2026 earnings estimate to $20.37 per share from $20.47.
Still, BofA expects Costco’s focus on value and its relatively higher-income customer base to help the retailer continue outperforming in a price-sensitive environment.
Costco shares have fallen about 1.3% over the past five days, 6.6% over the past month, and 7.7% over the past three months.
The stock is down roughly 7.5% over the past year, while remaining up about 3.3% year to date.
BofA expects strong Costco sales but some margin pressure
BofA forecasts Costco will report fourth-quarter adjusted earnings of $6.52 per share, slightly below the $6.55 consensus estimate cited in the firm’s report.
Its forecast incorporates net sales growth of 11.3%, which Costco has already disclosed for the quarter.
The bigger issue is what those sales are costing the company.
BofA expects fourth-quarter gross margin to decline by about 10 basis points as Costco continues to invest in prices while dealing with higher transportation costs.
Selling, general, and administrative expenses are expected to provide about 20 basis points of leverage.
This tradeoff is relevant because Costco has historically kept merchandise markups relatively low.
The retailer relies heavily on membership fees and high sales volumes rather than pushing aggressively for higher product margins.
For shoppers, preserving this model means Costco has an incentive to absorb or offset some cost increases rather than simply passing them along through higher prices.
Despite the expected margin pressure, BofA said Costco’s consistency should stand out amid continued consumer volatility.
U.S. comparable sales excluding gasoline increased 7.2% during the fourth quarter, compared with 6.8% in the third quarter.
The firm said Costco’s value-focused strategy and higher-income core customer base should help the retailer continue gaining share as consumers remain selective about where they spend.
Costco membership growth remains key focus
Costco’s merchandise prices are only part of the equation.
The retailer also needs to keep convincing customers that paying for membership remains worthwhile.
BofA said total member growth has slowed over the past several quarters.
It is partly because Costco opened fewer warehouses in Asia, and digital membership sign-ups have normalized after several years of stronger growth.
Membership growth was 4.1% in the third quarter.
BofA expects a 4%-5% medium-term growth rate to be more normalized for Costco.
The firm also expects management to continue leaning on new membership perks and the strength of Costco’s Kirkland Signature private-label brand to attract and retain customers.
Costco has recently been expanding one of those conveniences: delivery.
The retailer expanded its partnerships with DoorDash and Uber Eats this week.
Products from all U.S. Costco warehouses are now available through DoorDash, while Costco’s Uber Eats partnership expanded from 17 states to 47 states.
The added delivery options could appeal to shoppers looking to avoid increasingly crowded warehouses, a frustration that has become common enough to fuel dedicated complaint threads and communities on Reddit.
This could also make membership more useful for shoppers who value Costco’s prices and products but do not always want to navigate crowded parking lots, large stores, or bulk shopping trips.
Tariff refunds could help Costco keep prices low
Tariffs are another factor BofA is watching heading into earnings.
The firm said Costco largely mitigated tariff exposure across its general merchandise business last year.
Any tariff refunds received in the fourth quarter could provide an additional source of funding for price investments, according to BofA.
That would give Costco more flexibility to keep prices competitive rather than using all of the benefit to boost margins.
The issue has become increasingly important across retail as companies decide whether to use tariff refunds to lower prices, increase margins, fund employee investments, or cover other expenses.
BofA sees potential for special dividend
Costco’s growing cash balance creates another question heading into earnings: what the company will do with excess cash.
BofA expects Costco to announce another special dividend within the next few quarters.
Costco last paid a special dividend in January 2024 and has historically distributed special dividends every two to three years.
That January 2024 dividend produced a yield of roughly 2.4%.
BofA estimates Costco would need to pay approximately $22 per share to produce a similar yield at the current stock price.
It would represent an approximately $9.7 billion cash outflow.
The firm projects Costco will have about $20.4 billion in cash in the fourth quarter, giving the company substantial capacity for another payout if management chooses to make one.