


Headlines highlighting large retailers closing hundreds of stores frequently grab massive attention. However, sometimes beneath the flashy titles lies a story of a strategic store optimization that is yielding strong results.
That is the case of a 44-year-old iconic mall retailer, which, after 40 quiet closings, is projecting a return to profitability.
And while industry projections from Capital One Shopping Research suggest that the majority of traditional malls might close over the next decade, the retailer’s latest results confirm that certain shopping centers are still bringing in consumers.
Moreover, July 2026 Placer.ai data confirmed that foot traffic across all three mall formats increased year over year. However, performance varies widely by mall tier, prompting several major anchors to skip lease renewals and pivot toward open-air shopping centers.
Retail analyst Neil Saunders has argued that store closures and bankruptcies are recurring features of the retail cycle, rather than necessarily evidence of a failing industry. According to him, “they’ve happened at every stage of retail history and are, in fact, a sign that the market is working properly. But the temptation to link them to a dramatic narrative is often too great.”
Running a successful retail business for several decades requires the ability to adapt to the changing economic environments and shifting consumer habits. Tilly’s recent strategic moves suggest it is able to do so.
Tilly’s posts net sales growth, projects profitability
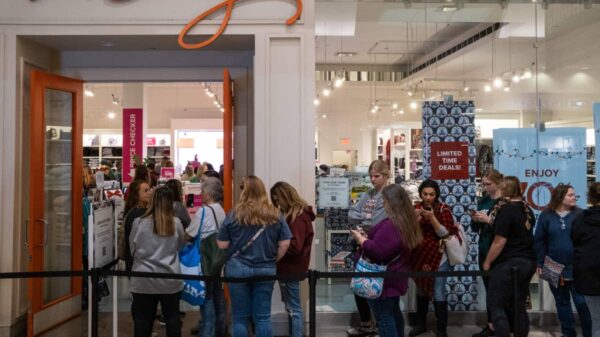
For decades, Tilly’s has anchored the youth retail scene by channeling the rebellious spirit of ’90s and 2000s skater style. The chain continues to draw younger shoppers with a heavy lineup of graphic tees, classic Vans kicks, and authentic Santa Cruz skate gear.
Tilly’s recently reported its second quarter of fiscal 2026 results. Total net sales were $163.5 million, up 8.1% compared to the same period in 2025.
More importantly, after closing 40 stores in roughly two years, its comparable net sales for the quarter increased by 12.1%. Comparable net sales include both physical stores and e-commerce.
Tilly’s Q2 fiscal 2026 earnings highlights:
- Net sales from physical stores were $129.0 million, an increase of 5.1%.
- Net sales from e-commerce were $34.5 million, an increase of 20.9%.
- Gross profit was $58.1 million, or 35.5% of net sales, compared to $49.1 million, or 32.5% of net sales, last year.
- Net income amounted to $8.4 million or $0.27 per diluted share, compared to a net income of $3.2 million, or $0.10 per diluted share in 2025.
- Source: Tilly’s Q2 Fiscal 2026 Earnings Document on SEC.gov
The above strong results come as the company ended the second quarter with 220 total stores, a decrease of 12 stores or 5.2%, compared to 232 total stores at the end of the second quarter last year.
My previous analysis for TheStreet, however, revealed a fuller picture: the retailer has closed even more stores over the last two years than the latest earnings report shows.
Why has Tilly’s previously closed 40 stores in two years?
Founded in 1982 as World of Jeans and Tops by Hezy Shaked and Tilly Levine, Irvine, California-based Tilly’s grew into a national retail staple before going public in May 2012 with a $124 million IPO.
The chain sells lifestyle apparel, footwear, and accessories, featuring roughly 200 third-party brands alongside its proprietary labels, including RSQ, Full Tilt, and West of Melrose.
As of early 2026, Tilly’s physical footprint spans three distinct shopping formats: 128 regional mall locations, 79 off-mall centers, and 16 outlet stores.
An analysis of Tilly’s previous reports revealed Tilly’s has closed 40 stores and opened 12 stores in around two years, reducing its footprint by 28 stores or 11%. Based on its latest earnings report, the brand has 220 operational stores remaining, down from the 248 it had at the beginning of the first quarter of fiscal 2024.
Tilly’s CEO Nate Smith framed the 21 closures in fiscal 2025 as a necessary structural realignment rather than a retreat.
Smith emphasized that scaling back required tough, disciplined decisions, but the move proved effective when the company achieved fourth-quarter sales growth despite operating 17 fewer net stores. He noted that management’s primary focus remains restoring historical sales productivity and operating performance across the remaining fleet.
“Returning to historical levels of store sales, productivity, and the operating performance this business is capable of is the goal we’re driving toward, and we know there is meaningful work still ahead of us to get to that point,” Smith said during Tilly’s fourth quarter and full year 2025 earnings conference call, as reported by MarketBeat.
Tilly’s management explained that margins also improved because of improved full-price selling and lower buying, distribution, and occupancy costs “due to decreased occupancy costs associated with reduced store count.”
What do Tilly’s closures mean for the retailer?
During the second quarter of fiscal 2026 earnings call, Smith first highlighted four consecutive quarters and 13 consecutive months of year-over-year comparable net sales growth.
The CEO then stressed that Tilly’s turnaround strategy has successfully returned the retailer to profitability.
The company earned nearly $2 million over the past four quarters and $400,000 so far in fiscal 2026. While these figures are modest, Smith highlighted them as crucial milestones for the business. He emphasized that the brand is now on track to deliver its first profitable full year since 2022.
Tilly’s is not the only mall retailer pursuing this strategy
In my extensive retail coverage for TheStreet, I recently reported on how several legacy mall retailers are executing strategic pivots similar to Tilly’s. Rather than signaling total financial collapse, these targeted store closures come in an effort to trim underperforming locations, protect profit margins, and adapt to shifting foot-traffic dynamics.
Fossil Group serves as a primary example of this shift. Over the past five years, the company closed more than 200 stores, including seven in early 2026 alone. By aggressively downsizing its physical footprint, Fossil expanded its gross margins and redirected resources toward high-margin digital channels.
Similarly, Shoe Carnival is closing dozens of stores to correct a recent merchandising mistake. The footwear retailer is using these closures to shed low-margin real estate and pivot back to its core audience of value-focused shoppers.
Specialty fashion and luxury retailers are following the same playbook:
- Michael Kors (Capri Holdings): Shuttered 139 stores over a three-year optimization window, stripping away excess real estate to focus on higher-yield flagship stores and online sales.
- Vera Bradley: Quietly closed 13 underperforming locations to reduce occupancy costs, optimize inventory distribution, and protect brand value.
- Parent company of Marshall Rousso & Misura: Closed 14 locations with additional consolidations planned, reallocating budget to consolidate footprint in high-density tourist hubs.
Across some of my recent reporting, the underlying theme is clear: rightsizing a store fleet is no longer just a defensive retreat. These retail brands are actively using targeted store closures as an operational tool to lower overhead, rebuild profitability, and position themselves for long-term survival.
Related: 102-year-old mall retailer quietly closes 25 stores
What’s next for Tilly’s? “We’re not finished”
Based on the Q2 fiscal 2026 earnings call transcript, Tilly’s is focusing heavily on maintaining its turnaround momentum through strategic real estate management and continued digital investments.
Smith expressed confidence in their trajectory, stating, “These are important milestones cleared in our turnaround story as we work towards producing what we currently believe will be our first profitable fiscal year since 2022. We are encouraged by our progress, but we’re not finished.”
Regarding real estate, management outlined a disciplined approach to managing the physical footprint. They expect to finish the fiscal year with 218 stores. This includes scheduled closures taking place in September, December, and January as leases expire.
At the same time, for fiscal 2027, the company is targeting 5 to 8 new store openings. However, management emphasized that this expansion is contingent upon achieving appropriate lease economics.
CFO Michael Henry also noted the financial balancing act of this strategy. He pointed out that while a reduced store count resulted in occupancy cost savings, those savings “were largely offset by higher e-commerce shipping expenses.”
How Tilly’s is changing the in-store experience
To complement its physical store strategy, Tilly’s is aggressively expanding its investment in digital and operational technology to improve efficiency. Management summarized plans to launch an “AI-driven smart inventory allocation tool.” This tool is designed to increase accuracy in balancing sizes and units across both the e-commerce platform and the physical store fleet.
Furthermore, the company plans to roll out new tech at the store level, by implementing RFID technology in its stores starting in early 2027. An initial focus will be on the footwear category to improve customer experience and in-store efficiency relating to size availability.
RFID uses smart-tagged labels to track inventory in real-time, allowing store staff to instantly verify if a customer’s shoe size is available without searching the backroom.
Bottom line, Tilly’s is demonstrating that, for some struggling mall retailers, shrinking the store base can be part of the path back to growth, provided the remaining stores become more productive and the company reinvests in the right channels.