
Micron Technology has turned into one of the clearest winners of the AI buildout, and its latest results show just how far the swing has gone. A company that spent years riding the ordinary ups and downs of the memory market is now posting numbers that look almost unrecognizable from where it stood a year ago.
The bigger question hanging over the stock is whether this run can keep going, or whether the same forces that have always eventually punished memory makers, new supply flooding in and pricing power fading, are about to catch up with Micron too.
Micron’s blowout quarter by the numbers
Micron’s fiscal third quarter results tell the story on their own. Revenue came in at $41.46 billion, up from $23.86 billion the prior quarter and just $9.30 billion in the same period a year earlier. That is a 346% year-over-year gain and 74% sequential growth. Adjusted earnings came in at $25.11 per share, beating the $20.78 consensus by more than 20%, according to CNBC.
That jump was not simply a matter of shipping more chips. Gross margin hit 84.9% on a non-GAAP basis, a company record, up from around 38% a year earlier. Rising average selling prices across both DRAM and NAND, combined with tight supply relative to demand, did most of the heavy lifting. GAAP net income reached $28.24 billion for the quarter, according to CNBC.
More Micron:
- Michael Burry increases his bet against popular chip giant
- Bank of America doubles down on Micron stock after AI bombshell
- Micron stock jumps as investors look beyond GPUs in AI chip trade
Management guided Q4 revenue to approximately $50 billion, plus or minus $1 billion, implying another 20% sequential step up from an already record quarter. Wall Street’s reaction was immediate. KeyBanc analyst John Vinh raised his price target on Micron to $1,750, citing tighter supply and higher prices across DRAM, NAND and high-bandwidth memory, with the firm forecasting DRAM prices to climb 15% to 20% in the third quarter and another 15% in the fourth, TheStreet reported.
Those price increases are not limited to one product category. KeyBanc expects NAND flash prices could rise 30% to 40% in the third quarter and another 15% in the fourth, with high-bandwidth memory prices potentially more than doubling next year.
Why this memory cycle looks different
Memory has always been boom and bust. Prices spike, manufacturers add capacity, oversupply kills the pricing, and everyone wonders why they bought at the peak. That pattern has followed Micron for decades and it is the reason even bullish investors have historically been reluctant to pay full price for memory earnings.
AI infrastructure may be challenging that pattern. Unlike past cycles driven by smartphones or personal computers, AI servers require dramatically more memory capacity, and because new semiconductor facilities take years to build, supply simply cannot expand fast enough to catch up with demand in the near term.
HBM is where the argument gets interesting. TD Cowen analyst Krish Sankar raised his price target to $1,500 from $660 and said memory in the AI era is structural, not cyclical. Mehrotra backed that up on the Q3 call. Micron can only fill 50% to two-thirds of demand from its biggest customers right now. That is not a pricing story. That is a supply story, CNBC reported.
The question of pricing power and new supply
Micron is not standing still on capacity. The company is preparing to launch HBM4 and HBM4e in the second half of 2026. Analysts believe it could help extend elevated pricing further, while S&P Global Ratings has already revised its outlook on Micron to positive, citing stronger cash flow and growing EBITDA.
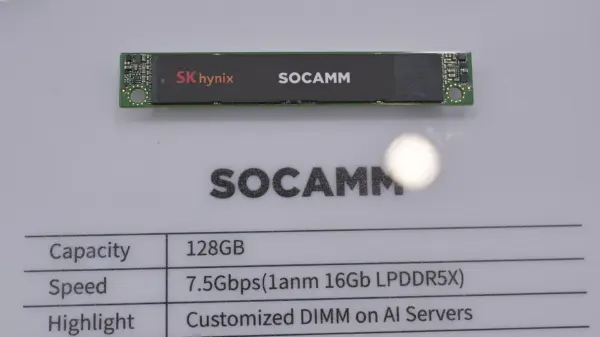
Competition has not gone away. In the HBM market, where the most profitable memory lives, SK Hynix holds roughly 50% of the market, Samsung around 33% and Micron approximately 18%, according to TheStreet. Micron is gaining share but is still a distant third in the segment driving the most margin expansion across the industry.
Morgan Stanley has modeled just how aggressive current pricing assumptions have become, projecting DRAM prices to surge 40% in the May quarter before rising another 15% the following quarter. Coordinated capacity additions from Micron, SK Hynix and Samsung remain the biggest wildcard. If all three ramp up production once new fabs come online, pricing could normalize faster than the current consensus expects, particularly if AI spending begins to moderate, TheStreet reported.
What this means for Micron investors
Price targets on Micron are all over the map. RBC Capital has theirs at $1,500, Mizuho at $1,300, and Citi recently raised to $1,300 from $1,150. The Street-high sits above $2,000. Averaged out, the consensus price target across analysts covering the stock clusters near $1,564, TheStreet reported.
The wide spread in targets tells you something. Nobody doubts how good the last two quarters were. The fight is over what comes next. Margins above 80% are extraordinary for a memory company. Whether they stay there depends on supply discipline from three manufacturers who have historically not been known for it.
September 30 is the next data point. Micron guided $50 billion for Q4. The number itself matters less than what management says about HBM demand and supply going into 2027. That is the conversation investors will be listening for.
Related: Citi doubles down on Micron stock ahead of earnings