
One thing trading has taught me is that just because a stock has fallen sharply doesn’t mean it can’t fall further.
I’ve watched prices drop to levels that looked attractive, only to see them keep falling. I have learned to be careful and not to rush into a trade simply because something looks cheap.
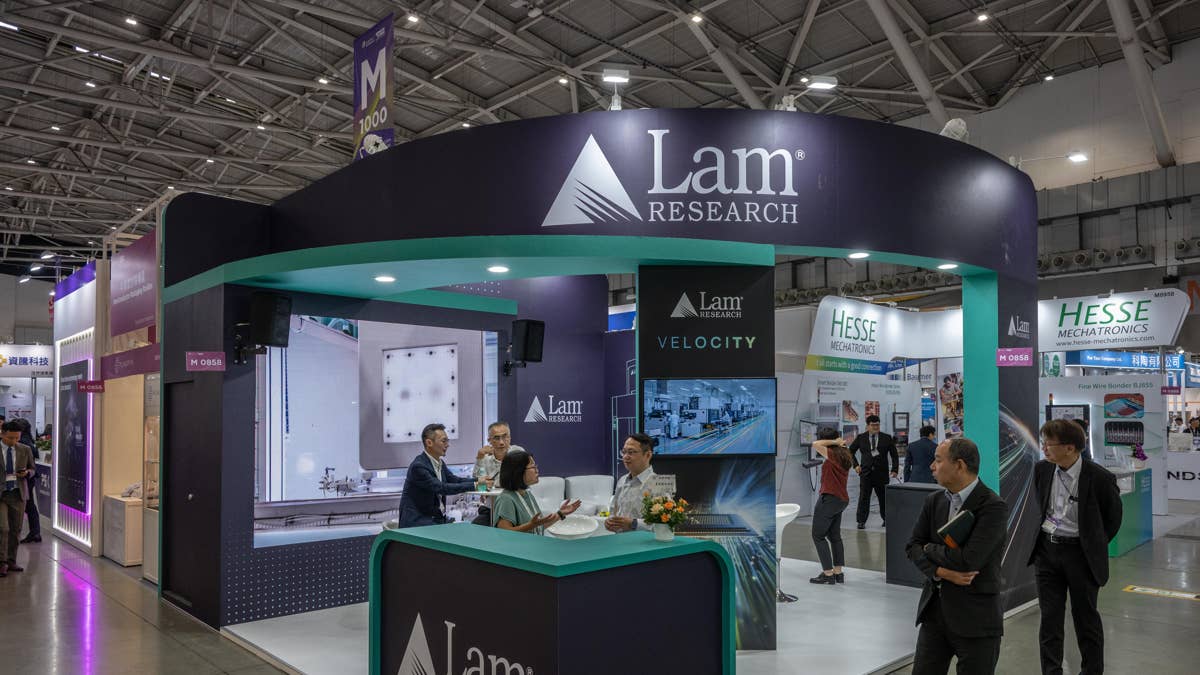
Jim Cramer offered “Mad Money” viewers a similar warning on Oct. 29, 2026, specifically about Lam Research stock (LRCX).
If you want to buy 100 shares of Lam, I don't want you to buy more than 25 right now. You buy 25, and then you wait another five days because right now the stock is in free fall, and I don't want you to get hurt.
Cramer had nothing but praise for the company itself, calling Lam Research “the best in the game of capital equipment.” The warning is about timing, not the business, and the trigger is Intel.
Also Read: Intel CEO reveals a PC problem as Goldman cuts stock target
Intel’s bad night became Lam’s bad day
“We have some bad numbers from Intel, really bad numbers, and I’m kind of bummed out about it,” Cramer said.
Intel reported Q3 fiscal 2026 results on Oct. 29 and guided Q4 revenue to between $15 billion and $16 billion, well short of the roughly $17.1 billion analysts expected.
Non-GAAP EPS guidance is $0.25 compared with a $0.43 consensus. Gross margin is expected to fall to 38% from 44.1%. Client PC revenue is projected to drop more than 20% from $8.1 billion as high memory prices choke PC demand.
An Oct. 14 fab explosion in Israel, which killed two workers, carries an estimated $300 million hit, with a similar impact expected in Q1. Intel shares fell roughly 30% on Oct. 30 and trade at $63.
More Semiconductors:
- Chip stocks set for $229 billion payday before Nvidia ships a GPU
- Bank of America makes bold chip call after AI sell-off
- Why Richard Ross is buying semiconductors after the AI pullback
I covered Intel in early September when Mizuho reset its price target to $92, and the debate then was whether the AI server story could offset PC weakness.
This quarter answered part of that. Data-center revenue is guided to about $8.4 billion, surpassing PC revenue, but the PC side dragged everything down.
Intel matters to Lam because it buys Lam’s etching and deposition tools. When chipmakers begin to tighten budgets, spending on new equipment is often among the first things to slow.
A strong Lam Research September 2026 quarter that still carried a warning
Lam’s own numbers were good. In Q1 fiscal 2027, reported Oct. 21, revenue hit a record $8.22 billion, up 54.4% year over year, beating the $8.14 billion consensus, according to ZACKS.
Non-GAAP EPS was $2.20, up 74.6%. Non-GAAP gross margin was 52.4%, and operating margin was 40.2%. Systems revenue rose 61.6% to $5.73 billion on foundry and NAND demand.
The stock fell anyway. On the earnings call, CFO Doug Bettinger said the December-quarter revenue guide of $8.6 billion would have been higher without near-term supply chain constraints, with some shipments possibly slipping into March.
Shares dropped more than 11% on that disclosure, according to Yahoo Finance.
As a trader, I’ve learned that even when a company’s fundamentals look strong, the market can still punish its stock over short-term concerns. That’s why I try not to rush into a falling stock. A good business doesn’t always mean it’s a good time to buy.
Why Lam is not just an Intel story
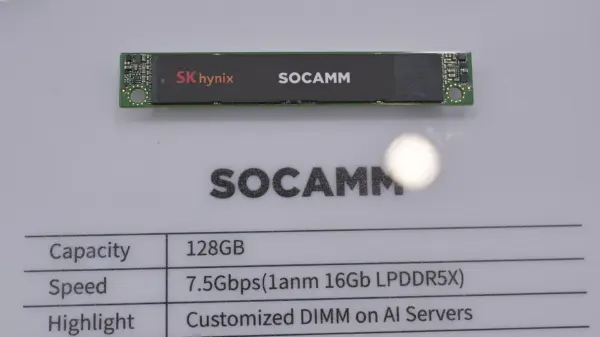
Intel is a major customer, but not Lam’s only one. Lam also sells to TSMC, Samsung, and SK Hynix and carries heavy exposure to NAND and DRAM, a market Intel left years ago. If TSMC takes share Intel loses, it tends to buy more Lam equipment.
The wider sell-off has added pressure. Amazon‘s weaker Q4 outlook stoked fresh doubts about the durability of AI-driven capital spending, the demand engine under Lam’s growth.
I wrote about that spending theme with Micron and SanDisk, where the thesis was memory tightness. The same logic helps Lam on the NAND side, which is why Cramer still likes the company.
His advice is therefore about pace instead of direction. Buying 25 shares now, then waiting a few more days, is a great way to avoid catching a falling knife while still owning a position if the stock steadies.
If Lam keeps sliding, you have cash to buy lower. If it rebounds, you are in.
The next questions for you as an investor are whether supply constraints ease enough to pull shipments back into December, and whether Intel’s weak guidance spreads to other equipment customers.
More Stocks News