
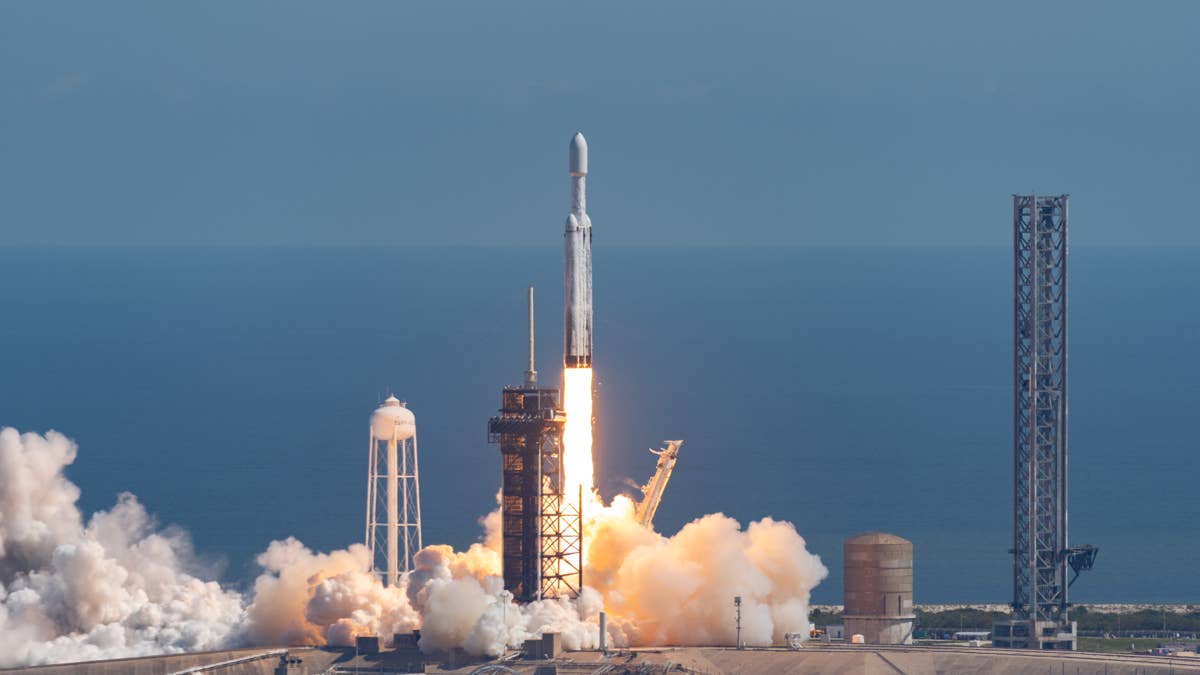
Elon Musk has taken investors on plenty of rollercoaster rides, but SpaceX (SPCX) shareholders have had an unusually compressed version of that experience since June.
The company completed the largest IPO in history, as reported by Reuters, pricing shares at $135 before closing its first day at $160.95. They later slid to $108 in early August before recovering toward $159 by early October.
For investors who bought into Musk’s newest public-market story, that tremendous choppiness has made the coming earnings report about much more than one quarter.
That said, in a note shared with me, Goldman Sachs has refreshed its view of SpaceX ahead of the company’s Q3 2026 earnings report, with particular attention to its fast-growing AI operation.
The issue is no longer simply whether Musk can build enormous amounts of compute. Goldman’s analysis centers on whether SpaceX can monetize that capacity at attractive rates while navigating a whole host of issues.
For shareholders, earnings may begin to separate the scale of Musk’s ambitions from the economics that support them.
Goldman sees AI becoming SpaceX’s next major growth engine
Goldman Sachs is heading into SpaceX’s Q3 earnings with a Buy rating and a $230 price target, up from $220, implying 45% upside from the stock’s recent price of $158.96.
The highlight of the report, though, is how aggressively Goldman has reset its expectations for what SpaceX could become beyond rockets and Starlink.
Goldman raised its total sales forecasts to about $51.6 billion for 2026, $127.5 billion for 2027, and $205.6 billion for 2028, increases of roughly 8%, 19% and 14% from its prior estimates. EPS forecasts also moved higher, to $1.30, $3.96, and $7.01, respectively.
The core driver is AI.
Goldman now expects SpaceX’s AI segment to generate roughly $27.3 billion in 2026, $90.4 billion in 2027, and $146.7 billion in 2028. The bank believes the company can reach about 2.4 gigawatts of terrestrial compute capacity by year-end 2026, then scale toward 7 GW in 2027 and 10.6 GW in 2028.
In my view, that clearly makes AI less of a side business and critical to the SpaceX investment case.
Goldman is not abandoning the original pillars, either. It still sees major long-term opportunities in launch, connectivity, and AI, potentially spanning trillion-dollar markets over five-plus years.
Starlink remains critical as Sensor Tower data compiled by Goldman showed monthly active users up 21% year over year, while app-download growth accelerated to 59% in September.
The bigger question heading into earnings is whether SpaceX can monetize its rapidly expanding compute footprint as effectively as Goldman now assumes, while keeping Starlink and launch growth moving alongside it.
Musk says AI could eclipse SpaceX’s core businesses as Starlink targets telecom
Musk’s own view of SpaceX’s future is perhaps even more aggressive than Goldman Sachs’ latest forecast.
In an August all-hands meeting, Musk called AI an “extremely important part of SpaceX’s future” and predicted that the company’s “AI revenue will exceed all other SpaceX revenue probably in September.”
That’s a bold call, to say the least, as AI was still smaller than Starlink just one quarter earlier. SpaceX reported $7.81 billion of Q2 revenue, including about $2.56 billion from AI and $4.29 billion from Connectivity, which includes Starlink.
More SpaceX:
- Morgan Stanley doubles down on SpaceX stock for investors
- SpaceX analyst plots path to bold $100 billion claim
- JPMorgan resets SpaceX price target after earnings
AI revenue nevertheless grew roughly 247% year over year, driven primarily by new infrastructure contracts.
What stands out to me is that Musk isn’t positioning AI as merely another SpaceX business; the model looks tightly interconnected.
Starship lowers launch costs, Starlink supplies global connectivity, and SpaceX’s terrestrial and eventually orbital infrastructure supplies compute. Goldman now expects AI to become the company’s largest revenue segment, with hosting alone potentially generating $40 billion to $45 billion annually in 2027-28.
Starlink, meanwhile, is beginning to challenge a much older industry.
On SpaceX’s Q2 call, management said AT&T (T), Verizon (VZ), and T-Mobile US (TMUS) generate roughly $600 billion annually combined. They also argued that Starlink Mobile could take customers from them.
Musk said SpaceX believes its system can provide connectivity “probably better and higher bandwidth than what is currently available from cellular providers.”
Starlink added more than 1.7 million consumer subscribers in Q2, held a monthly ARPU of around $66, and ended June with roughly 10,200 operational broadband and mobile satellites.
I think that combination is critical to the investment case. SpaceX is no longer asking investors to value rockets, satellites, and AI separately. Musk is increasingly building them as parts of the same infrastructure platform.
SpaceX stock needs execution to justify the premium
I feel that SpaceX stock isn’t cheap enough for investors to ignore execution risk, even with the growth Goldman Sachs expects.
At Goldman’s reference price of $158.96, SpaceX trades at roughly 122 times 2026 earnings, 40 times 2027 earnings, and 23 times 2028 earnings. EV/EBITDA falls from about 55-times in 2026 to 25-times in 2027 and 15-times in 2028.
In other words, the valuation only starts to look more reasonable if SpaceX delivers the steep earnings ramp embedded in current forecasts. Free cash flow is also expected to remain negative through 2028, reflecting enormous capital spending.
That is why I would focus less on whether Q3 simply beats expectations and more on three things: AI monetization, Starlink growth, and the pace of compute buildout.
If management shows that hosting demand remains strong, Starlink continues to add users, and power/GPU constraints ease, I think the premium can be defended. If any of those weaken, the stock’s valuation leaves little room for disappointment.
Before earnings, I see SpaceX as a high-expectation stock where execution matters more than narrative.
Related: Nvidia stock flashes massive signal as Wall Street leans in