
Hawkish Fed rate hikes boost the US Dollar while sluggish global growth, Middle East tensions, and tech sell-offs drive volatility.
Federal Reserve Tightening Expectations and US Dollar Strength
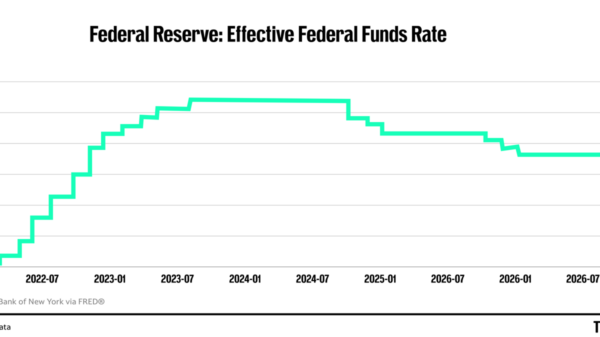
Hotter-than-expected US inflation data, including a third consecutive upside surprise in October core CPI, alongside decidedly hawkish rhetoric from Federal Reserve officials, has fundamentally reshaped interest rate expectations. Policymakers such as Chair Kevin Warsh, Cleveland Fed President Beth Hammack, Kansas City Fed President Jeff Schmid, and Governor Christopher Waller have signaled that inflation remains uncomfortably above the 2% target and that financial conditions are not yet sufficiently restrictive. As a result, interest rate markets are increasingly pricing in an aggressive tightening cycle featuring three consecutive rate hikes in December, January, and March—with debate even emerging over a potential 50-basis-point move in December—that could lift the effective Fed funds rate toward 4.6% from its current 3.75%–4.00% range. This widening policy divergence has propelled the US Dollar Index (DXY) to 2026 peaks near 103.50–103.60, putting heavy pressure on major currencies and commodities. The Euro is testing critical psychological support at 1.1000 amid widening two-year swap differentials and Eurozone fiscal concerns, the Australian Dollar has fallen to 10-month lows near 0.6740, and non-yielding gold has retreated to 13-month lows around $3,850 per troy ounce as elevated Treasury yields diminish its appeal.
Divergent Growth and Inflation Dynamics Across Major Economies
Outside the United States, major economies are grappling with a difficult mix of sluggish economic growth and lingering price pressures that complicates central bank decision-making. In Japan, preliminary third-quarter GDP data revealed an unexpected stall at 0.0% quarter-on-quarter (with some estimates noting a 0.1% contraction), weighed down by weak net exports and a second consecutive quarterly decline in household consumption. Despite this economic softness, Bank of Japan board member Hajime Takata emphasized the need to act swiftly on rate hikes to curb upward price shifts, keeping a December increase from the current 1.25% policy rate firmly on the table. A similar tension is playing out in the Eurozone, where September industrial production rose just 0.2% after three straight monthly declines, remaining well below 2025 levels due to ongoing weakness in energy-intensive sectors and structural headwinds like global competition, even as business sentiment surveys stay optimistic. Meanwhile, in Canada, three consecutive monthly job losses and softer third-quarter growth argue for monetary patience, yet headline inflation holding at 3.1% and elevated producer prices keep the Bank of Canada poised for a potential 25-basis-point hike to 2.75% in December.
Geopolitical Escalation, Equity Volatility, and Currency Intervention Risks
Heightened geopolitical instability and shifting risk sentiment are introducing cross-currents across energy, equity, and foreign exchange markets. Escalating US–Iran tensions—marked by reports of tankers striking mines in the Strait of Hormuz, an Iranian drone attack targeting a US military base in Bahrain, and the deployment of the USS Theodore Roosevelt to the region—have kept supply disruption fears and upside inflation risks alive, even as front-month WTI crude oil futures fluctuate near the $86 per barrel mark. At the same time, a broad sell-off in technology shares from Asia to Wall Street, occurring ahead of Nvidia’s closely watched November 17 earnings report following Jensen Huang’s exit, has spurred safe-haven flows. These defensive flows have uniquely benefited the Japanese Yen, helping it outperform its peers and drift toward 159.50 against the US Dollar despite Japan’s weak GDP figures. Yen gains are further reinforced by heightened trader caution over potential currency intervention by Japanese authorities after USD/JPY recently tested the closely watched 160.00 threshold.
Top economic events for next week:
11/16/2026 20:00:00 — RBNZ Financial Stability Report (NZD): This semi-annual report assesses the resilience of New Zealand’s financial system and flags potential risks in housing, banking, and household debt. Because it can influence how aggressively the Reserve Bank of New Zealand adjusts monetary policy without destabilizing borrowers, it sets the opening tone for the New Zealand Dollar early in the week.
11/17/2026 00:00:00 — RBA Governor Bullock Speech & Meeting Minutes (AUD): Delivering remarks immediately followed by the Reserve Bank of Australia’s meeting minutes, Governor Michele Bullock provides direct insight into the central bank’s thinking on inflation and interest rates. With the Australian Dollar hovering near multi-month lows, traders rely on these twin releases to gauge whether the RBA will maintain a restrictive stance or soften its policy outlook.
11/17/2026 02:00:00 — RBNZ Inflation Expectations (QoQ) (NZD): As a primary forward-looking gauge of price pressures in New Zealand, business inflation expectations heavily influence the RBNZ’s rate decisions. A higher-than-anticipated reading reinforces the need for tighter monetary policy to keep inflation anchored, often triggering immediate volatility in NZD pairs.
11/17/2026 07:00:00 — UK Employment Data: Claimant Count Change & ILO Unemployment Rate (GBP): This comprehensive labor market release measures jobless claims, employment growth, and wage trends across the United Kingdom. Because persistent wage growth and tight labor conditions keep services inflation elevated, these figures are critical for determining the Bank of England’s upcoming interest rate path and driving near-term Pound Sterling momentum.
11/17/2026 13:30:00 — US Retail Sales (MoM) & Retail Sales Control Group (USD): Serving as the primary barometer of US consumer spending—which accounts for roughly two-thirds of US economic activity—this report tests whether higher borrowing costs are finally cooling demand. Strong consumption data reinforces market bets on further Federal Reserve rate hikes, adding fuel to the US Dollar’s rally.
11/17/2026 23:50:00 — Japan Merchandise Trade Balance & Exports (JPY): Following third-quarter GDP data showing that net exports were a major drag on Japan’s stalled economy, October trade figures provide an updated check on external demand and import costs. The release helps traders evaluate Japan’s economic health alongside ongoing speculation over Bank of Japan rate hikes and potential currency intervention.
11/18/2026 07:00:00 — UK Consumer Price Index (YoY) & Core CPI (GBP): Inflation remains the single most decisive factor for Bank of England monetary policy. Headline and core CPI prints will confirm whether UK price pressures are cooling toward target or proving sticky, directly shaping interest rate expectations and sparking sharp moves in GBP.
11/18/2026 14:25:00 — ECB President Lagarde Speech (EUR): With EUR/USD testing major psychological support near 1.1000 amid widening rate differentials against the US Dollar, markets closely scrutinize Christine Lagarde’s remarks for policy clues. Her tone on Eurozone inflation, fiscal risks, and economic resilience can either stabilize the Euro or accelerate its downward trajectory.
11/18/2026 15:00:00 — BoE Governor Bailey Speech (GBP): Speaking hours after the release of the UK CPI report, Bank of England Governor Andrew Bailey offers immediate central bank reaction to the latest inflation and jobs numbers. His commentary helps markets calibrate expectations for upcoming rate decisions, making his appearance a major catalyst for Sterling volatility.
11/18/2026 19:00:00 — FOMC Minutes (USD): As the marquee US event of the schedule, the minutes from the Federal Reserve’s October policy meeting reveal the internal debate behind the Fed’s recent rate hike and hawkish pivot. Traders dissect the text to assess how broadly policymakers support consecutive rate increases into early 2027, making it a pivotal driver for the US Dollar, Treasury yields, and gold.
The subject matter and the content of this article are solely the views of the author. FinanceFeeds does not bear any legal responsibility for the content of this article and they do not reflect the viewpoint of FinanceFeeds or its editorial staff.
The information does not constitute advice or a recommendation on any course of action and does not take into account your personal circumstances, financial situation, or individual needs. We strongly recommend you seek independent professional advice or conduct your own independent research before acting upon any information contained in this article.